Corporate bonds often attract investors with promises of high and regular yields. However, more important than the promises is understanding who you are actually lending money to and how they intend to repay it. What should you check before investing, and which warning signs should never be ignored? Go through our checklist with us.
It is important to keep repeating that corporate bonds are an exceptionally risky investment instrument. Even a regulated bond issue can result in substantial losses.
In 2025, corporate bonds with a total value of nearly CZK 32 billion ended up in insolvency. According to data from the forensic agency Surveilligence, as many as 43% of issuers go bankrupt within three years of their first bond issue.
This is a trend that has been worsening over time and is affecting an ever-larger segment of the market. Retail investors account for approximately 80% of corporate bond issues on the Czech capital market, and this share continues to grow. Combined with the rapid increase in the volume of bonds being issued, this means that not only is the market itself expanding, but so too is the absolute volume of potential losses faced by retail investors.
Why corporate bonds are so appealing
Corporate bonds are particularly attractive because they promise a combination of high and seemingly predictable yields. Offering documents often advertise fixed interest rates of around 6% to 12% per annum, significantly exceeding the returns available from standard bank products.
Another key factor is that investors initially receive yields on a regular basis, often monthly or quarterly. This initially creates the impression of a stable income stream, similar to rental income or dividends. From a psychological perspective, this is a crucial factor. If you receive the first payment as promised, you are likely to view the investment as both sound and safe, even though there is always a possibility that the issuer may later fail to meet its obligation to repay either the interest or the principal amount of the bond.
Quality of issuers
In recent years, the Czech market has been flooded with corporate bonds issued by both large and small companies. Over the past 12 years, the market has grown almost tenfold, from less than CZK 16 billion in 2013 to CZK 145 billion last year. However, the growth in bond issuance has also been accompanied by an increasing number of troubled cases. It is important to keep repeating that corporate bonds are an exceptionally risky investment instrument. Even a regulated bond issue can result in substantial losses.
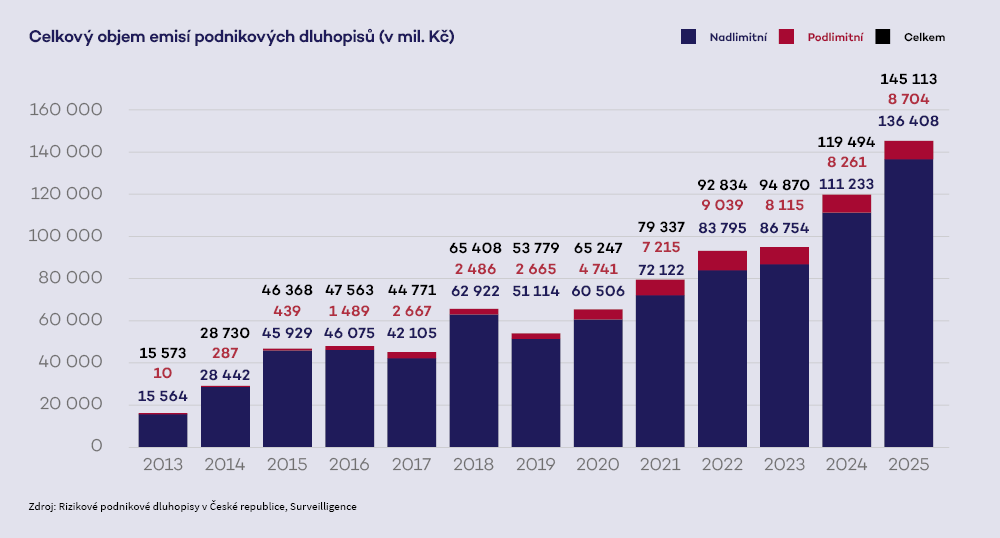
The data show that these are not isolated incidents. A legislative amendment adopted in 2012 simplified the bond issuance process and removed the requirement for issuance terms to be approved by the regulator. As a result, a segment of the market emerged in which a large number of issuers operate with limited track records, minimal equity capital and no access to bank financing.
Bond issues distributed through unregulated distribution channels are up to seven times riskier. Approximately 14% of bonds distributed through unregulated channels are currently in insolvency, compared with around 2% of bonds distributed through regulated channels. A significant portion of these bonds is inherently unsuitable for inexperienced retail investors, yet they are often marketed directly to them.
Moreover, more than half of all bonds mature within three years, creating a high dependence on continuous refinancing. Some issuers repay existing obligations solely with funds obtained from new investors, in a structure resembling a so-called bond Ponzi scheme. In certain cases, this leads investors to gradually increase their exposure to the same issuer. And that is where the problem begins.
High-profile cases
One example is the Brno-based energy group GEEN, which presented investments in power plants to its roughly 2,000 predominantly retail investors as safe and conservative. However, the group reported a loss of approximately CZK 195 million in 2023, while its annual interest expenses alone amounted to around CZK 327 million. By the end of 2024, GEEN had stopped making timely payments of both interest and principal, and insolvency proceedings were initiated in March 2025. The group’s total indebtedness reached approximately CZK 2.925 billion.
A similar scenario affected other issuers as well. In September 2025, the RSBC Group publicly acknowledged that it was unable to meet its due liabilities out of bonds and promissory notes and commenced a restructuring process. In November 2025, reorganisation proceedings were approved for its parent company, RSBC Holding. The holding company’s reported debts totalled approximately CZK 1.9 billion, and the goal of the reorganisation was to return around 40% of creditors’ claims.
A similar fate befell the Solek Holding group that engages in solar energy projects. In March 2025, it informed investors that it did not have sufficient funds to repay bonds with a total value of nearly CZK 200 million. In April 2026, creditors approved a reorganisation plan providing for the entry of a new investor. The recovery rate for unsecured creditors is expected to be minimal, despite registered claims amounting to billions of Czech crowns.
When a creditor becomes a ‘gambler’
When a company comes under financial pressure, even the very economic nature of an investment can change. In the case of Alemar Food Group, for example, proposed changes extended beyond yield, interest payments and maturity dates. They even included a proposal to convert bondholders’ claims into non-voting investment shares. For investors, this represents a fundamental shift in position. Instead of remaining creditors with a clearly defined claim, they may find themselves in a situation where their return depends largely on whether the company manages to stabilise its business and secure a path to further growth. In other words, an instrument that was intended to function as a predictable loan can suddenly become an even more uncertain bet on the company’s future.
And there is one more point that is often overlooked. The purchase of a bond is not the end of the story. Investors who pay no attention to their bonds may one day discover that the terms have changed, and that they were not involved in the process. That is why bondholders should remain vigilant throughout the entire life of the issue. Investors should monitor the issuer’s disclosures, verify whether the company is meeting its obligations, and keep track of bondholders’ meetings, where decisions directly affecting the investment are often made. The higher the promised yield, the more attention investors should pay to the quality of the issuer, the group structure, the purpose of the financing, and whether any security has been provided.
How to identify a high-risk corporate bond issuer
So how can you tell whether a company you are considering entrusting with your money may be too high-risk? There is no simple test. A high-risk issuer does not always take the form of an “empty shell” company. Sometimes it is a newly established business with no track record. At other times, it may be a well-known group with an established market presence, a portfolio of completed projects, and a recognised name.
The problem often becomes apparent only when you start looking into how the issuer intends to use the funds, what assets the company actually owns, and what sources it will rely on to repay its obligations. A single red flag does not necessarily indicate a problem. However, if several red flags appear at the same time, it is worth examining the documentation much more closely.
You do not need to understand every detail of the project. But you should understand the basic story behind the money. Where the money goes today, where it is expected to come from in the future, and what will happen if things do not go according to plan.
A prospectus is not a guarantee of safety
A common misconception is that a bond whose prospectus has been approved by the Czech National Bank must be a safe investment. In reality, approval of a prospectus does not mean that the Czech National Bank has assessed the issuer’s business plan or its ability to repay its obligations. Rather, the prospectus is intended to provide investors with the information necessary to form their own independent judgment. It is, however, a source of information, not a guarantee that investors will get their money back.
Likewise, not every bond issue without a prospectus should automatically be viewed with suspicion. Some offerings may fall within one of the exemptions from the prospectus publication requirement. In its Ten Commandments for Retail Investors, the Czech National Bank also reminds investors that corporate bonds are not insured against default risk. If an issuer is unable to pay its liabilities, investors become creditors, and the amount they ultimately recover will depend on the company’s assets, its other debts, and the nature of potential security.
What does the issuer itself own?
A website full of visualisations and photographs may look convincing, but for creditors it means very little in itself. What matters is what the company identified as the issuer in the bond terms and conditions actually owns. Not the group as a whole. Not the company that promotes the project.
You may encounter structures in which the bonds are issued by a holding company or a special-purpose vehicle that subsequently passes the funds on to an operating company. It is often that operating company that owns the real estate, manufactures products, or otherwise generates the profits. If the operating company runs into difficulties, its assets will first be used to satisfy its own creditors, including its obligation to the bond issuer, which is often only one creditor among many. As a result, a holder of bonds issued by a parent company, or by another group company depending on the group’s actual structure, may have no direct legal claim to the operating company’s assets.
Such an arrangement is not necessarily problematic in itself. What matters is whether investors have a specific link to those assets or cash flows, whether through a guarantee from the operating company, a pledge over shares, a mortgage over real estate, or another mechanism that is clearly described in the documentation. This is because the consolidated results of the group as a whole do not, in themselves, answer the key question of what will ultimately remain available to satisfy the claims of the particular issuer’s creditors.
Vague purpose of bond issue
The more broadly the purpose of the bond issue is described, the more questions you should be asking. What exactly will the company use the money for? When is the project expected to start generating revenue? What happens if construction is delayed or no tenant is found? Risk tends to be higher where a company finances a long-term project with short-term debt. A project that is not expected to generate revenue for several years may be financed through a bond maturing in just two years. In such cases, the issuer often assumes that it will repay the bond either through the sale of an asset or by launching a new bond issue. That strategy may work, but all it takes is a market downturn or a delay in the project for the original plan to unravel.
“Security” is not a magic word
The label “secured bond” may create the impression that the investment is almost risk-free. What matters, however, is not the word “security” itself. What matters is exactly what is secured, whether the security actually exists, and what its real value is.
Security may take the form of real estate, shares in a company, receivables, or a guarantee provided by another company. Each type offers a different level of protection. In the case of real estate, an estimate of the project’s future value is not enough. Investors should know whether the pledge has actually been created, whether the asset is already subject to prior-ranking pledges in favour of a bank, and at what price the asset could realistically be sold in a distressed situation.
It is equally important to know what exactly is secured. It is not automatically the case that all bondholder claims, i. e. the nominal value, the yield and any contractual penalties, are “secured”. The secured debt may cover only the principal, or even just a portion of it, for example up to 50% of the nominal value. For that reason, investors should verify from the documentation exactly which claims are covered by the security. It is also worth knowing who is responsible for administering the security and under what conditions that person or entity may act.
A bond is a loan to a company, not a fixed-term deposit
In conclusion, investors should approach bonds with caution and always keep in mind that they are not purchasing a “yield-generating product”, but rather lending money to a specific company.
Unlike a bank deposit, where funds are placed with a bank operating within an entirely different regulatory and economic framework, a corporate bond means that the investor personally bears the credit risk of the particular issuer.
The right question, therefore, is not how much a bond will yield, but where the company will actually get the money to repay it. If the issuer has a stable business, a reasonable level of indebtedness and sufficient cash flow, a bond investment may make economic sense. However, if the business depends on the future success of a project, further refinancing, or a continuous inflow of new capital, the situation looks very different.
On paper, you may see promised returns of 7-9% per annum or even higher. In reality, however, you may be taking on a level of risk that is closer in nature to venture capital investing, a type of risk typically assumed by experienced investors who fully understand that they could easily lose their entire investment.
The costs of selling and distributing the bonds also come into play. Corporate bonds do not sell themselves. Many bond issues are supported by marketing campaigns, distribution networks, public offering administration, and various other transaction-related costs. The Surveilligence study points out that in the case of so-called below-threshold bond issues, i.e. those not subject to the requirement to publish a prospectus approved by the regulator (the Czech National Bank), a further concern may be that up to one-third of the funds raised in the first year is not used for the intended investment purpose, but rather for the administration and sale of the bond issue and for the issuer’s interest obligations. So do not just focus on the coupon rate, but also on the economics of the issue as a whole.
FAQ
What should you check before investing in a corporate bond?
Find out who is actually issuing the bond, what the issuer owns, how it generates revenue, and how the money will be used. It is also important to understand the specific source from which interest and principal will be repaid.
How can you identify a high-risk corporate bond?
There is no single reliable indicator. Red flags may include an unclear purpose of the bond issue, dependence on further financing, an opaque issuer structure, or an unclear source of funds for repayment.
How can you find out whether a company will be able to repay a bond?
It is important to verify whether the issuer has sufficient income and a realistic source of funds to pay both interest and principal. Particular caution is required where repayment depends on the success of a future project or on a new bond issue.
What does it mean when a corporate bond is secured?
Security may take the form of real estate, shares in a company, claims or a guarantee. However, it is important to verify its actual value and also which bondholder claims it genuinely covers.
What happens if a company fails to repay a corporate bond?
The investor is in the position of a creditor, and the recovery of his funds depends on the issuer’s assets, its other debts and any security provided. In some cases, the company may subsequently enter insolvency proceedings.
Key contacts
Jan Šturm
Partner
He specialises in dispute resolution before civil courts and in arbitration proceedings, as well as insolvency proceedings. Jan has been involved in disputes with an aggregate value of several hundred billion Czech crowns. He has extensive experience in representing clients primarily in legally and technically complex cases, including those that involve foreign elements.
Martin Stančík
Associate Partner
He specialises in banking, finance and capital markets, with a particular focus on the regulatory aspects of providing financial services, including licensing proceedings before the Czech National Bank. He also has experience advising on debt financing transactions.